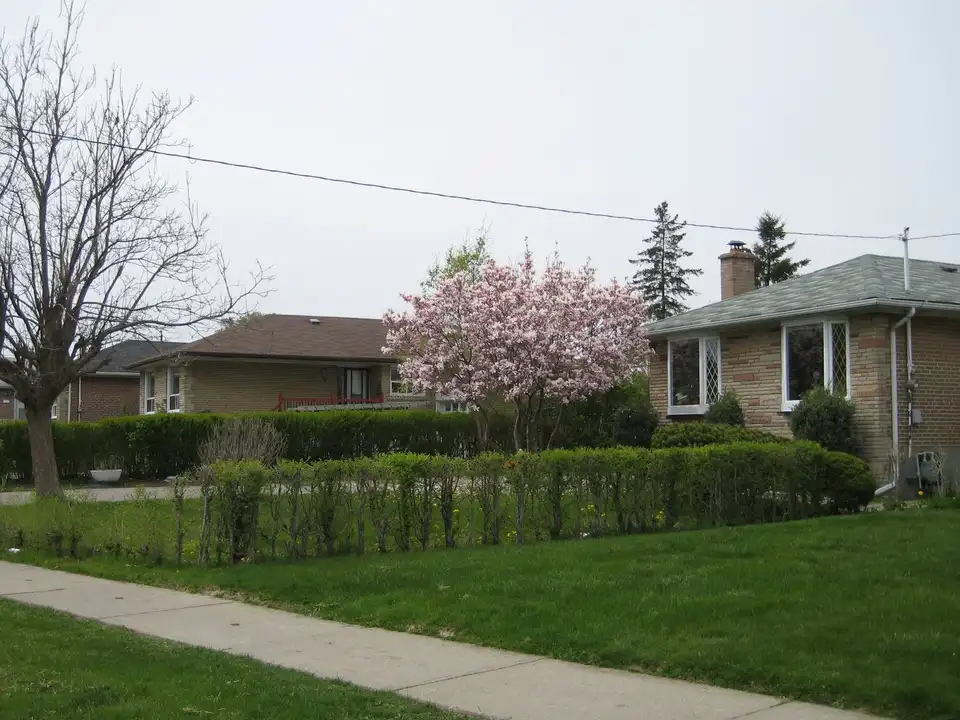
ReverseMortgageEtobicoke.ca walks Rexdale homeowners 55 and older through how a Rexdale reverse mortgage works on the kind of house the neighbourhood is known for: a brick bungalow or a storey-and-a-half house from the 1950s. You borrow against the house, go on living in it and make no required monthly mortgage payments.
Prices in north Etobicoke are lower than near the lake, so the dollar figures here are smaller than in the south. They are still large enough to clear a mortgage, pay for a new furnace or cover years of property taxes.
Rexdale’s first streets, 1951 to 1954
Developer Rex Heslop bought the 100-acre Wardlaw farm in 1951. The first 40 homes, on Allenby Avenue, were sold on April 24, 1952 for about $9,000 to $10,000 each, and Old Malton Road became Rexdale Boulevard in 1954 (Etobicoke Historical Society).
Those early homes were bungalows and storey-and-a-half houses, and many still stand. In the 2021 Census, 54.0% of dwellings in Rexdale-Kipling were built in 1960 or earlier, and another 33.5% from 1961 to 1980 (City of Toronto, 2021 Neighbourhood Profiles).
A house that age qualifies like any other, and the money can pay for changes that help you stay, as paying for home care in Etobicoke explains. Condition still counts, because the appraiser walks through every room and a house in poor repair may not be approved.
Same Rules, Same Protections as a Kingsway House
A reverse mortgage is a percentage of the appraised value, set by the youngest owner’s age. On a lower value, the same percentage gives a lower dollar amount, but the rules, the rate and the protections are the same as on a Kingsway house.
More than half of Rexdale-Kipling owners (57.0%) still had a mortgage in 2021, and in Elms-Old Rexdale the figure was 59.4%. For those owners, the first job of a reverse mortgage is usually to pay that mortgage off and end the monthly payment.
Example: A Rexdale-Kipling Bungalow
For example, take an owner aged 70 in a 1950s bungalow off Kipling Avenue. Detached houses in Rexdale-Kipling sold for a median of $870,000 from April to June 2026, across 17 sales (TRREB, Q2 2026).
At 70, the ceiling is up to about 53% of $870,000, or about $460,000. The owner still owes $150,000 on a mortgage and wants $30,000 for a new furnace and windows.
At closing, the $150,000 mortgage is paid off and the $30,000 goes to the owner’s bank account, for $180,000 in total. The monthly mortgage payment ends that day, and the other $280,000 of the ceiling is not borrowed, so no interest is charged on it. Your own figure is one step away in the Etobicoke reverse mortgage calculator.
Tax help to check before you apply
The City of Toronto and the province both run programs for older homeowners, and each has its own income test. Checking them first shows whether you need to borrow for property taxes at all.
Toronto’s relief on the yearly increase
Households with combined income up to $62,000 can apply to cancel or defer each year’s property tax increase (City of Toronto). Cancellation is for owners 65 and older, or 60 to 64 on GIS, whose assessment is below $975,000. The 2026 deadline is November 2, and you reapply every year.
Your assessment is still based on January 1, 2016 values, so compare the figure on your MPAC notice, not today’s price, with $975,000 (MPAC). The relief covers only the increase: on the City’s average home, assessed at $692,140, the 2026 increase was $92 (City of Toronto, 2026 budget report).
Qualifying households also get 30% off the water bill if they use less than 400 cubic metres a year.
Ontario’s grant
Homeowners 64 and older can receive as much as $500 a year from the province’s Senior Homeowners’ Property Tax Grant, with the full amount for income up to $35,000 (single) or $45,000 (couple) (Ontario). You claim it on your tax return, and it is never repaid.
How the relief and a reverse mortgage fit
It is usually one or the other: the City’s deferral or a reverse mortgage. A deferral is added to the tax roll and becomes due when the home is no longer owned by an eligible person (Toronto Municipal Code, ch. 767). More detail is in Etobicoke property tax help for seniors.
If W10 Prices Keep Falling
TRREB’s September 2026 benchmark for a detached house in W10, the district that includes Rexdale, was $855,100, down 8.04% from a year earlier (TRREB Market Watch, September 2026). The condo apartment benchmark was down 16.23%.
A lower value means a lower ceiling, because the amount is set from the appraisal done after the lender approves you. Equity is not certain to shrink: interest adds to what you owe, yet values that recover or rise over the years often make up some or all of it.
Condos in Elms-Old Rexdale
Condo apartments in Elms-Old Rexdale sold for a median of $385,000 in the second quarter, across 10 sales. At 65, that is up to about $195,000, and condo fees stay yours along with property taxes. Building reviews are explained in reverse mortgages for Etobicoke condos.
The lender looks at the building and its condo corporation as well as the unit. The same building can be accepted by one lender and declined by another, which is why the Etobicoke mortgage broker page explains comparing all four.
Rexdale home values and what they could provide
Prices: TRREB Community Housing Market Report, Toronto West, Q2 2026 (April to June); W10 benchmark from TRREB Market Watch, September 2026. Amounts are the most you could qualify for at that age, from the same age table as the reversemortgagebroker.ca calculator, rounded to the nearest $1,000, before anything you owe is paid off. The largest amounts come at a higher rate, and the lender's appraisal of your own home sets the real figure.
These are TRREB's April to June 2026 median prices for Rexdale-Kipling and Elms-Old Rexdale, with the September 2026 W10 detached benchmark of $855,100 for comparison. Anything you owe is paid off first, and your own appraisal sets the real figure.
Streets and pockets of Rexdale
Richard helps owners in every part of Rexdale and the communities beside it, including:
- Rexdale-Kipling
- Elms-Old Rexdale
- Thistletown
- Mount Olive-Silverstone-Jamestown
- West Humber-Clairville
- Kingsview Village-The Westway
- Humber Heights-Westmount
Places locals know
- Allenby Avenue, where the first 40 Rexdale homes were sold in 1952
- Rexdale Boulevard, called Old Malton Road until 1954
- Humber College station, the western end of Line 6 Finch West
- The Humber Arboretum and the Humber River trails
- Thistletown's Village Green, Etobicoke's first public park (1896)
- Kipling Acres, the City of Toronto's long-term care home on Kipling Avenue
Getting help from home in Rexdale
Richard Hopkins, Mortgage Broker, helps Rexdale owners by email, phone and video call, and a relative can be copied on every email. Only two steps happen in person: the appraiser visits the house, and you meet your own lawyer. Many owners choose a lawyer close to home, along Rexdale Boulevard or Kipling Avenue.
Reasons Rexdale owners look into it
- A broker who compares everything: Every reverse mortgage lender in Canada compared, plus HELOCs and refinances, so the recommendation fits your situation.
- Paying for home care: Private care hours, a stair lift or a main-floor bathroom, paid from your home's value so you can stay in it.
- Garden suite or multiplex: A second home on your lot for family or a caregiver, paid for from your house with no required monthly mortgage payments.
- Condo owners: Condo apartments and condo townhouses from Humber Bay Shores to Rexdale can qualify, with no required monthly mortgage payments.