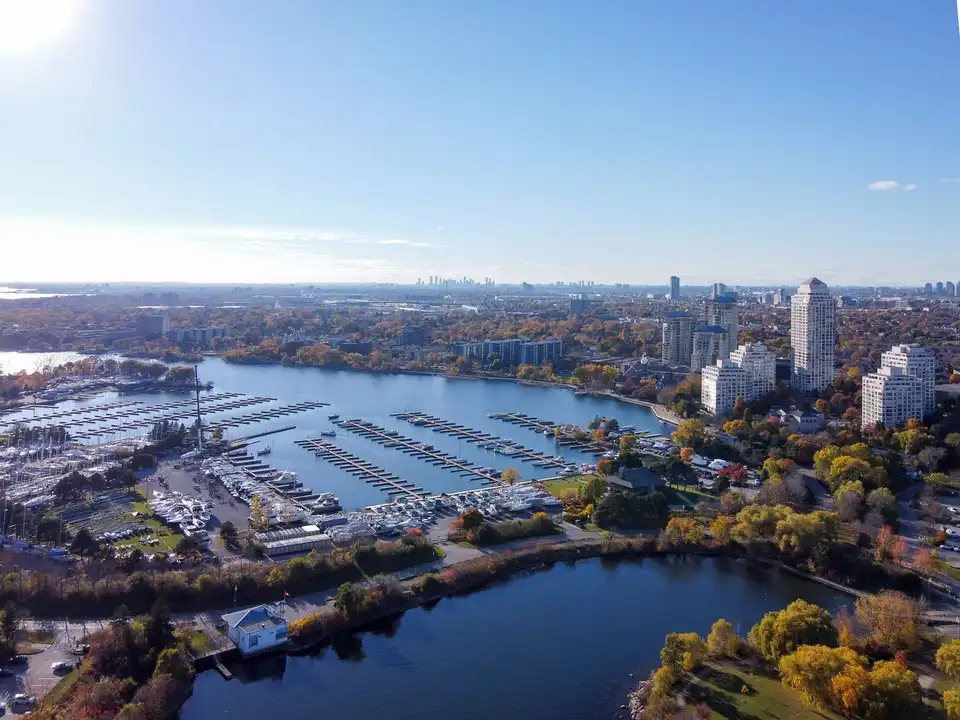
ReverseMortgageEtobicoke.ca walks through the Etobicoke condo reverse mortgage for owners 55 and older, from the lakeshore towers to the condo townhouses further north. A condo apartment or a condo townhouse can qualify, and you keep living in it with no required monthly mortgage payments.
Your condo fees, property taxes, home insurance and upkeep stay yours. The reverse mortgage pays off any mortgage you still have and gives you money for the rest.
Where Etobicoke’s condo owners live
Condos are a big part of Etobicoke home ownership, most of all along the lake. In Ward 3, Etobicoke-Lakeshore, 43.9% of owner households owned a condo in 2021, against 36.5% across Toronto (City of Toronto Ward Profiles, 2021 Census).
Humber Bay Shores is almost all towers. Only 0.1% of its homes were single-detached houses in 2021, and about 85% of them were built after 1980 (City of Toronto Neighbourhood Profiles, 2021).
The condo market is busy in other parts of Etobicoke too. From April to June 2026, Mimico recorded 124 condo apartment sales at a median of $609,000. Islington-City Centre West, which takes in the towers around Kipling and Six Points, recorded 109 at a median of $518,000 (TRREB Community Report, Toronto West, Q2 2026).
Condo townhouses count as condos too. Long Branch had 15 condo townhouse sales in the same three months, at a median of $749,000.
What an Etobicoke condo could give you, by district
TRREB splits Etobicoke into districts W06 to W10. The table uses each district’s September 2026 benchmark for a condo apartment, times the age guide: up to about half the value at 65 and up to about 58% at 75.
| District | Condo apartment benchmark | Up to about, at 65 | Up to about, at 75 |
|---|---|---|---|
| W06 (Mimico, New Toronto, Long Branch, Alderwood) | $607,800 | $307,000 | $351,000 |
| W08 (Islington-City Centre West, The Kingsway area, West Mall) | $531,000 | $268,000 | $307,000 |
| W09 (Humber Heights, Richview, The Westway) | $450,600 | $228,000 | $260,000 |
| W10 (Rexdale and north Etobicoke) | $408,400 | $206,000 | $236,000 |
Source: TRREB Market Watch, September 2026. These are ceilings, not quotes, and lenders set condo amounts a little differently than for a house. Your own unit’s appraisal sets the final amount, and anything you still owe is paid off first out of the same money.
Benchmarks move. The W10 condo apartment benchmark was down 16.23% from a year earlier, while W06 was down 1.17%. You can see the latest district figures in the Etobicoke home prices update for September 2026.
What lenders check in an Etobicoke condo building
A lender looks at three things: your unit’s value, the building with its condo corporation, and the location. Every lender covers the whole City of Toronto, so for an Etobicoke condo the building matters most.
Your status certificate
The status certificate is the condo corporation’s official summary of its finances. It shows your fees, the reserve fund (money saved for big repairs) and any special assessments.
A lender reviewing a building can also look at:
- How healthy the finances and reserve fund are compared with the repairs ahead
- Any special assessment already announced
- Whether the condo corporation’s rules allow the mortgage
- Whether the monthly fees are reasonable
- The building’s state of repair
The four lenders don’t weigh these the same way. One building can get a yes from one lender and a no from another, which is why every lender gets checked against your building.
Condos that don’t qualify
Leasehold condos usually don’t qualify, because the land under the tower belongs to someone else. Co-ops usually don’t either, since you hold shares rather than the unit itself. If you’re not sure which you have, ask first. Your purchase papers or status certificate show which kind you have.
Condo fees and special assessments stay yours
The reverse mortgage replaces any mortgage payment. It does not replace condo fees, and the condo corporation still bills you each month.
Rising fees are a good reason to plan ahead. You can take the money as a lump sum, as regular monthly deposits, or a mix of both, and interest is charged only on money you actually take.
If a special assessment has already been announced, it can often be paid off from the money at closing. Richard checks this with the lender for your building.
The rate, the guarantee and your equity
Rates run 6.23% to 6.94% (advertised 5-year fixed rates across the four lenders, checked September 17, 2026). Interest is added to the balance instead of being paid each month, compounded twice a year.
Your equity isn’t certain to shrink. Interest adds to what you owe, but condo price growth often offsets some or all of it over the years.
You can never owe more than your condo’s fair market value at the time the mortgage becomes due, as long as property taxes, insurance and upkeep are kept up. This is typically called the no negative equity guarantee.
The mortgage becomes due when you sell, when the last borrower moves out for good, or when the last borrower passes away. If two spouses are both borrowers, nothing changes while one of them still lives in the unit.
Staying in your condo or buying another one
Staying where you are involves no land transfer tax, because you’re not buying anything. Buying in Etobicoke means paying Ontario’s land transfer tax and the City of Toronto’s own tax on top.
On a $607,800 condo, each tax comes to $8,631, so a repeat buyer pays $17,262 in total (Ontario land transfer tax; Toronto municipal land transfer tax). The guide to downsizing in Etobicoke sets out the full cost of a move.
A reverse mortgage on your condo usually costs about $2,000 to $3,500 in one-time costs, including your own lawyer. Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada and also looks at a HELOC or other option. You get a recommendation based on your situation, even if it’s not a reverse mortgage.
What Richard handles for you
- A free estimate for your unit that doesn't affect your credit
- Every reverse mortgage lender in Canada checked against your building
- A plain read of your status certificate and what lenders look for in it
- A check that your unit is a standard condo, not leasehold or a co-op
- A plan for condo fees, special assessments and property taxes
- The best deal for your condo and goals, by email
- Your adult children copied on emails whenever you like
- Help finding your own lawyer for independent legal advice
Etobicoke guides on this topic
- Downsizing in Etobicoke: Land Transfer Tax and Every Other Cost of Moving
- Etobicoke Property Tax for Seniors: Due Dates, Relief Programs and Grants
Sources
Numbers last checked October 16, 2026.
- TRREB, Market Watch, September 2026 (condo apartment MLS HPI benchmarks and sales for districts W06 to W10, released October 6, 2026)
- TRREB, Community Housing Market Report, Toronto West, 2026 Q2 (April to June 2026)
- City of Toronto, 2023 Ward Profiles (2021 Census): condo share of owner households, Ward 3
- City of Toronto, 2021 Neighbourhood Profiles: Humber Bay Shores and Etobicoke City Centre dwelling types and building ages
- Government of Ontario, Calculating land transfer tax (updated April 22, 2026)
- City of Toronto, Municipal Land Transfer Tax rates and fees (modified April 7, 2026)