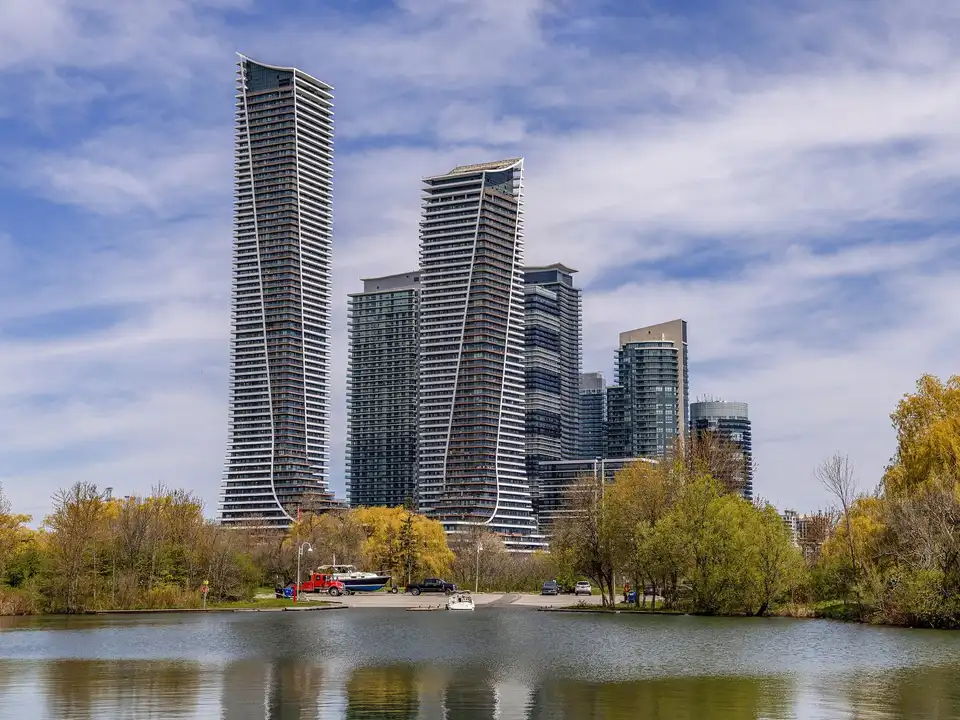
ReverseMortgageEtobicoke.ca explains how owners of Humber Bay Shores condos can borrow against their unit with a reverse mortgage and keep living by the lake.
Humber Bay Shores is a condo community. In the City of Toronto’s 2021 Neighbourhood Profiles, 0.1% of its homes were single-detached houses, 3,565 of its 22,605 residents were 65 or older (15.8%), and owners put a median value of $670,000 on their homes (City of Toronto, 2021 Neighbourhood Profiles).
From motel strip to condo towers
The towers stand on what was once the “Motel Strip” on Lake Shore Boulevard West. In 1995 the province approved a plan to replace it with condos, Marine Parade Drive, the Waterfront Trail and parkland (Etobicoke Historical Society).
The name Humber Bay Shores was chosen by the condo owners themselves. The Palace Pier tower, from 1978, stands where an earlier Palace Pier burned down in 1963 (same source).
That mix of ages matters for a reverse mortgage. A tower from the late 1970s and one finished decades later can stand a short walk apart, and a lender reviews each building on its own record.
What a lender checks in a Humber Bay Shores building
Every Canadian reverse mortgage lender accepts standard condos. Before approving, each one reviews three things: your unit, the building and its condo corporation, and the location.
Your unit
An appraiser visits the unit and confirms what it is worth. The amount available is then set from that appraised value, so two units in the same tower can qualify for different amounts.
The condo corporation
The corporation’s rules must allow the mortgage. A lender also wants healthy finances, fees that make sense and a well-kept tower.
Lenders differ on which towers they accept. The same Humber Bay Shores unit can get a different answer from each of them, which is why every lender is compared for your building. More on this is in reverse mortgages for Etobicoke condos.
Leasehold units and co-ops
A standard condo registered in your name qualifies. Leasehold condos (where the land is not owned with the unit) and co-ops (where you own shares, not the unit) usually don’t qualify, so ask first.
Example: A Widower at 75
For example, picture a widower, 75, in a Humber Bay Shores condo apartment worth $607,800, TRREB’s September 2026 benchmark for a W06 condo apartment (TRREB Market Watch, September 2026). His mortgage is paid off. His condo fees went up again this year, and his pension has not kept pace.
At 75, he could borrow up to about 58% of the value, which is about $351,000 on $607,800. He takes $30,000 at closing to rebuild his savings, then a deposit of $1,000 a month. Interest is charged only on the money he has actually received.
He makes no required monthly mortgage payments. Interest is added to his balance twice a year. Rising home prices often offset some or all of it over time, though W06 condo apartment benchmarks were 1.17% lower in September 2026 than a year earlier, so nothing is guaranteed.
He can never owe more than his home’s fair market value at the time the mortgage becomes due, as long as property taxes, insurance and upkeep are kept up. This promise is typically called the no negative equity guarantee.
What stays your job after closing
A reverse mortgage removes the monthly mortgage payment. It does not remove the costs of owning a condo.
- Condo fees. They are still due every month. A set monthly deposit from the reverse mortgage can help cover them.
- Property tax. The City of Toronto bills your unit like any other home. Owners 65 and older with a household income up to $62,000 may qualify for City relief, explained in property tax help for Etobicoke seniors.
- Home insurance. Your own unit policy has to stay in force.
- Living there. The condo must stay your main home. If you’re away more than 30 days in a row, arrange for someone to check the unit.
Thinking of moving into Humber Bay Shores instead
Some Etobicoke house owners look at these towers as their next home. Buying here means paying Ontario’s land transfer tax and the City of Toronto’s municipal land transfer tax. On a $607,800 condo, a repeat buyer pays about $8,631 to each, or $17,262 in total (Government of Ontario; City of Toronto).
A reverse mortgage on the home you already own involves no land transfer tax, because nothing is bought. The full list of moving costs is in downsizing in Etobicoke and land transfer tax.
Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada for your building, then emails you the best deal for your home and goals. His help costs you nothing, because the lender pays the brokerage once the mortgage funds. You can test your own figures first in the Etobicoke reverse mortgage calculator.
Humber Bay Shores home values and what they could provide
Prices: TRREB Market Watch, September 2026 (MLS® HPI benchmarks, City of Toronto districts, p. 26). Amounts are the most you could qualify for at that age, from the same age table as the reversemortgagebroker.ca calculator, rounded to the nearest $1,000, before anything you owe is paid off. The largest amounts come at a higher rate, and the lender's appraisal of your own home sets the real figure.
TRREB has no separate Humber Bay Shores figure, so these are the September 2026 benchmarks for district W06, Etobicoke's lakeshore district. Lenders set condo amounts a little differently than for a house, so treat these as a guide. Your own unit's appraisal sets the real figure.
Streets and pockets of Humber Bay Shores
Richard helps owners in every part of Humber Bay Shores and the communities beside it, including:
- Marine Parade Drive
- Park Lawn Road at Lake Shore
- Mimico
- Stonegate-Queensway
- The Queensway
- New Toronto
Places locals know
- Humber Bay Park West
- Humber Bay Park East
- Humber Bay Butterfly Habitat
- The Waterfront Trail
- Palace Pier condominium (1978)
- Humber Loop
Getting help from home in Humber Bay Shores
Richard Hopkins, Mortgage Broker, helps Humber Bay Shores owners by email, phone and video call. Your son, daughter or anyone else you choose can see his emails too. Only two steps happen in person: the appraiser comes up to your unit, and you meet your own lawyer. Many owners choose a lawyer close to home, along Lake Shore Boulevard West or near Park Lawn Road.
Reasons Humber Bay Shores owners look into it
- Condo owners: Condo apartments and condo townhouses from Humber Bay Shores to Rexdale can qualify, with no required monthly mortgage payments.
- A broker who compares everything: Every reverse mortgage lender in Canada compared, plus HELOCs and refinances, so the recommendation fits your situation.
- Paying for home care: Private care hours, a stair lift or a main-floor bathroom, paid from your home's value so you can stay in it.