ReverseMortgageEtobicoke.ca looks at what a New Toronto reverse mortgage means for owners 55 and older in the old factory town on the lake. Most homes here are older houses and semis, and many of their owners are still paying a mortgage.
Built for factory workers
New Toronto’s first plan was registered on January 16, 1890, and it became a village in 1913 (Etobicoke Historical Society). It was laid out for industry, with workers’ homes close to the plants.
The Goodyear plant opened in 1917 and closed on May 31, 1987; at one time it employed 1,350 people. In 1918 the New Toronto Housing Commission built 42 English cottage-style homes on Eighth Street for factory workers (same source).
The plants are gone, but many of the houses remain. In 2021, 44.5% of New Toronto’s homes had been built in 1960 or earlier (City of Toronto, 2021 Neighbourhood Profiles).
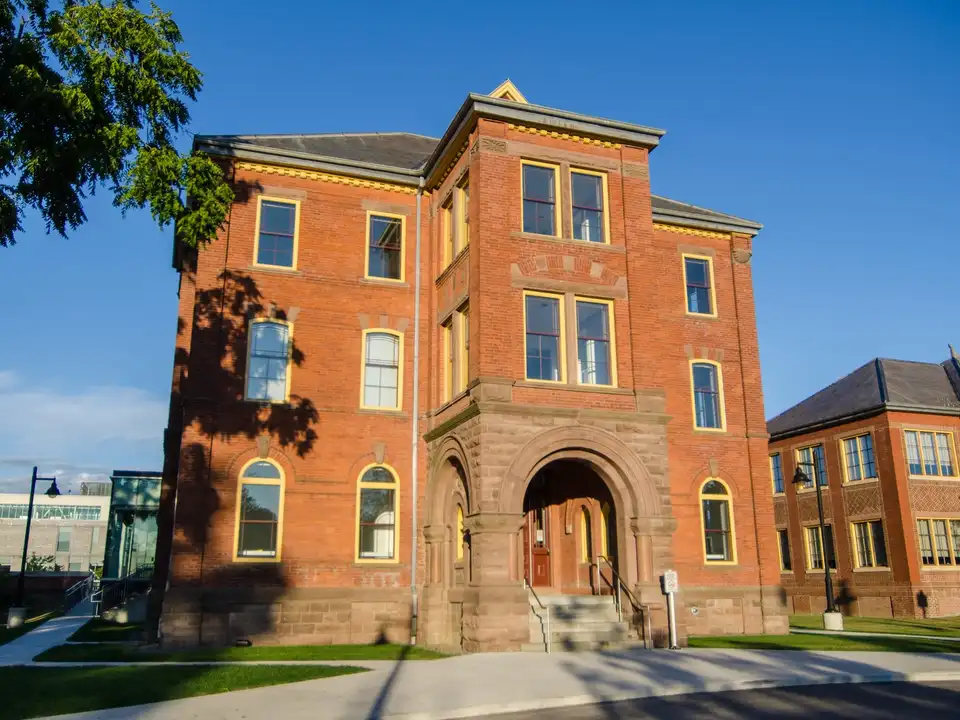
The cottages of the former Lakeshore Psychiatric Hospital, now part of the Humber Polytechnic Lakeshore Campus, were designed by Kivas Tully and built from 1889 to 1894, then restored between 1992 and 2008 (Lakeshore Grounds Interpretive Centre).
What a lender looks at on a New Toronto house or semi
Detached houses, semis, townhouses and condos all qualify for a reverse mortgage. For a house or a semi, the lender reviews the value, the condition and the location.
Semis
You own a semi-detached house and its land outright, the same as a detached one, and the shared wall doesn’t stop a reverse mortgage. TRREB counted only 3 semi sales in New Toronto from April to June 2026, so an appraiser’s figure for your own semi will matter far more than that median.
Age versus upkeep
A house built in the factory years can still qualify. What counts is how well it has been kept, because a lender can decline a home in major disrepair.
When a mortgage is still owing
New Toronto had the lowest rate of home ownership in Etobicoke in 2021, at 43.9% of households, and 64.4% of its owners still had a mortgage (same Neighbourhood Profiles). For an owner in their late 60s or 70s, that monthly payment can take a large part of a pension.
A reverse mortgage always pays off the existing mortgage first, at closing. The balance owing has to fit inside the amount your age and home qualify for.
Example: A Semi at 75
For example, an owner, 75, has a New Toronto semi worth $1,110,000, the median for semis in TRREB’s New Toronto community from April to June 2026 (TRREB Community Housing Market Report, Toronto West, Q2 2026). She still owes $180,000, and her mortgage comes up for renewal next spring.
At 75, her ceiling is about 58%: up to about $641,000 on $1,110,000. The $180,000 is paid off at closing, and up to about $461,000 more stays available to her.
Timing matters here. Paying off a fixed bank mortgage partway through its term can bring a break fee that often runs into the thousands, so closing the reverse mortgage near her renewal date usually avoids that charge.
Her monthly mortgage payment stops. Property tax, home insurance and upkeep remain her bills. Interest is added to what she owes, and home price growth often offsets some or all of it, so her equity is not certain to shrink.
Advertised 5-year fixed rates across the four lenders were 6.23% to 6.94%, checked September 17, 2026. Her set-up costs, paid once, are usually about $2,000 to $3,500 in total, including about $800 to $1,200 for her own lawyer’s independent legal advice.
If one spouse needs long-term care
The City of Toronto runs Lakeshore Lodge, a 150-bed long-term care home on Lake Shore Boulevard West in New Toronto (City of Toronto, long-term care homes). From July 1, 2026, a basic room in any Ontario long-term care home costs $2,129.17 a month (Government of Ontario).
When both spouses are on the reverse mortgage, nothing changes while one of them still lives in the house. More on applying and wait lists is in long-term care in Etobicoke.
City tax help for New Toronto owners
The City of Toronto’s tax relief is open to households with income up to $62,000. Owners 65 and older with an assessment under $975,000 can have the year’s tax increase cancelled, and the deferral option postpones the increase without interest until the home is no longer theirs. The 2026 deadline is November 2, 2026 (City of Toronto; 2026 budget report). Owners 64 and older with lower incomes can also claim Ontario’s Senior Homeowners’ Property Tax Grant, worth up to $500 a year (Government of Ontario).
Details are in property tax help for Etobicoke seniors.
As well as comparing every reverse mortgage lender in Canada, Richard Hopkins, Mortgage Broker, arranges HELOCs and refinances, as the Etobicoke mortgage broker page explains. The printable checklist lists the papers to gather, and the Etobicoke reverse mortgage calculator gives a first figure for your own house.
New Toronto home values and what they could provide
Prices: TRREB Community Housing Market Report, Toronto West, Q2 2026 (New Toronto, PDF p. 40). Amounts are the most you could qualify for at that age, from the same age table as the reversemortgagebroker.ca calculator, rounded to the nearest $1,000, before anything you owe is paid off. The largest amounts come at a higher rate, and the lender's appraisal of your own home sets the real figure.
These are TRREB's April to June 2026 median prices for New Toronto. Three semi sales is a very small sample, and lenders set semi amounts a little differently, so the appraisal of your own home matters far more than that median.
Streets and pockets of New Toronto
Richard helps owners in every part of New Toronto and the communities beside it, including:
- Eighth Street cottages
- Islington Avenue south
- Kipling Avenue south
- Lake Shore Boulevard West
- Mimico
- Long Branch
- Alderwood
Places locals know
- Colonel Samuel Smith Park
- Humber Polytechnic Lakeshore Campus
- Lakeshore Lodge (City of Toronto long-term care home)
- LAMP Community Health Centre on Fifth Street
- The Waterfront Trail
Getting help from home in New Toronto
Richard Hopkins, Mortgage Broker, helps New Toronto owners by email, phone and video call, and relatives can be copied on any email. Only two steps happen in person: the appraiser visits your house, and you meet your own lawyer. Many owners choose a lawyer close to home, along Lake Shore Boulevard West or up Islington or Kipling Avenue.
Reasons New Toronto owners look into it
- A broker who compares everything: Every reverse mortgage lender in Canada compared, plus HELOCs and refinances, so the recommendation fits your situation.
- Paying for home care: Private care hours, a stair lift or a main-floor bathroom, paid from your home's value so you can stay in it.
- Garden suite or multiplex: A second home on your lot for family or a caregiver, paid for from your house with no required monthly mortgage payments.